
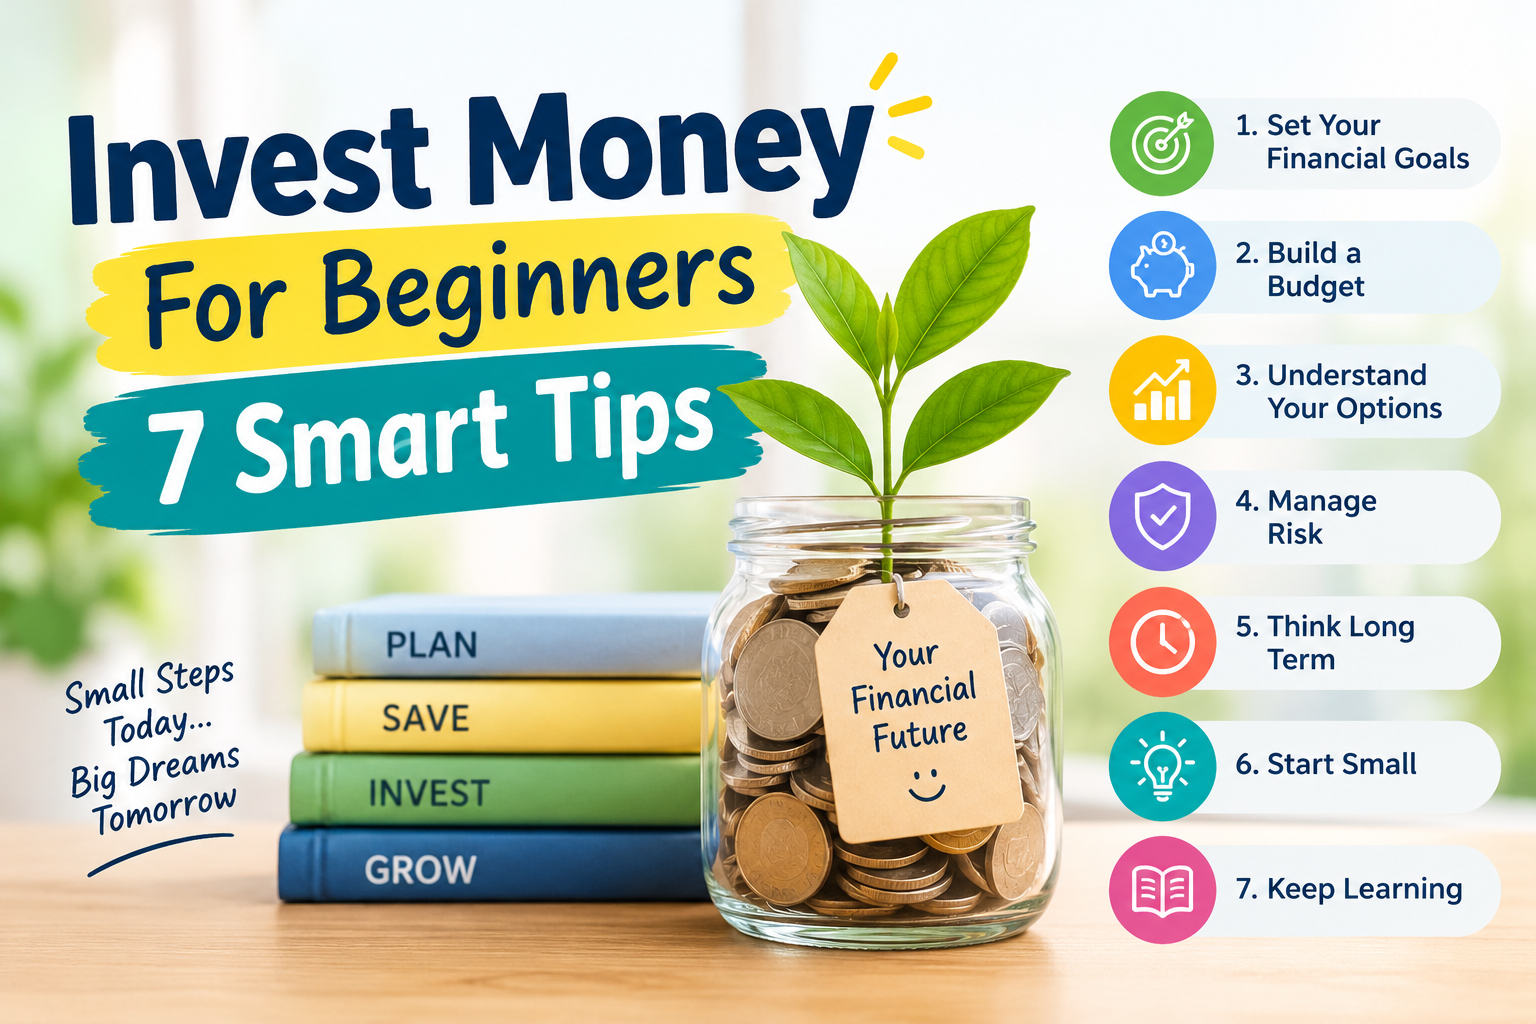
Invest Money For Beginners 7 Smart Tips, Invest Money For Beginners can seem like a difficult topic when you are just starting to manage your money. You may wonder how much money you need, which investments you should choose, and whether you could lose your savings. These are common questions, and you do not need to know everything before taking your first step. What matters most is learning the basics and making careful decisions.
Investing is a way to put money into assets that may grow in value or provide income over time. However, growth is never guaranteed, and some investments can lose value. The best approach is to understand your goals, prepare for unexpected expenses, and choose investments that match your financial situation and comfort with risk.
This guide explains seven smart tips in simple English. You will learn how to set goals, build an emergency fund, understand investment risk, compare investment options, avoid common mistakes, and create a practical plan for the future.
Table of Contents
Quick Summary: Invest Money For Beginners
| Key area | What to do |
|---|---|
| Set a goal | Decide what you want your money to achieve. |
| Prepare first | Build emergency savings and manage expensive debt. |
| Start small | Invest an amount you can afford to leave invested. |
| Understand risk | Learn how investments can rise or fall in value. |
| Diversify | Avoid depending on a single investment. |
| Stay consistent | Follow a realistic plan instead of chasing trends. |
| Review wisely | Check progress periodically and adjust when needed. |
The central lesson is simple: you do not need to become rich before you begin investing. You need a clear plan, a basic understanding of risk, and the patience to make informed decisions over time.
Invest Money For Beginners 7 Smart Tips-What Does It Mean to Invest Money?
Before following the seven tips, it is important to understand what investing actually means. When you invest, you use your money to buy an asset that may increase in value or provide income in the future. Examples include stocks, bonds, mutual funds, exchange-traded funds, and certain types of property.
Saving and investing are not the same. Saving usually means keeping money somewhere accessible for short-term needs or emergencies. Investing means accepting some level of risk in the hope of earning a return over time. The value of investments can rise or fall, and you may lose some or all of the money you invest. Investor.gov explains these basic differences in its introduction to investing.
Think of a person who receives a monthly income and wants to build a better financial future. They might first save enough to handle unexpected expenses. After that, they could invest a manageable amount regularly toward a long-term goal. This approach separates money needed for safety from money intended for future growth.
The most important point is that investing is not a shortcut to becoming wealthy overnight. It is a process of making informed choices, understanding risk, and giving suitable investments time to work.
Tip 1: Set Clear Financial Goals Before You Invest
One of the smartest ways to invest money for beginners is to decide why you want to invest. Without a clear goal, it becomes easy to follow other people’s advice, buy investments without research, or change your plan whenever the market moves.
Your financial goal gives direction to your decisions. For example, you might want to save for education, buy a home, start a business, prepare for retirement, or build long-term wealth. Each goal has a different time frame and may require a different investment approach.
Separate Your Short-Term and Long-Term Goals
Short-term goals are those you expect to achieve relatively soon. These might include paying for a course, replacing a vehicle, or preparing for a planned expense. Money needed soon generally belongs in suitable, accessible savings or lower-risk options rather than highly volatile investments.
Long-term goals give you more time to handle market ups and downs. Retirement planning is one example. Depending on your circumstances, a diversified investment portfolio may help you work toward such goals.
Before investing, write down three things: what you want to achieve, when you need the money, and how much you may need. These details will help you choose an appropriate strategy.
Make Your Goals Realistic
Suppose your goal is to build a fund worth 20,000 units of your local currency over five years. Instead of searching for an investment promising extraordinary returns, calculate how much you can contribute regularly and consider how different returns might affect the outcome.
Remember that investment returns are uncertain. Your plan should not depend on receiving a particular return every year. It should be flexible enough to handle periods of weak performance.
A useful habit is to review your goals once or twice a year. Your income, expenses, family needs, and priorities may change. Adjust your plan when necessary, but avoid making sudden decisions simply because markets are rising or falling.
Tip 2: Build an Emergency Fund Before Investing Heavily
A common beginner’s mistake is investing nearly all available money without keeping enough cash for unexpected expenses. This can create problems when an urgent bill arrives or regular income stops.
An emergency fund gives you a financial cushion. It can help cover necessary expenses during unemployment, a medical emergency, urgent home repairs, or another unexpected event. Without this reserve, you may have to sell investments at an inconvenient time.
How Much Emergency Savings Should You Have?
A useful starting goal is to save enough to cover several months of essential expenses. Your personal target depends on your circumstances.
For example, someone with stable employment and low monthly expenses may need a different reserve from someone who earns an irregular income or supports several family members. A reserve covering three to six months of essential expenses is a common guideline, not a rule that fits everyone.
Keep emergency money in a suitable account that allows reasonably quick access. Check the account’s safety, withdrawal conditions, and applicable protections in your country.
Manage Expensive Debt
Before increasing your investments, review any high-interest debt you have. Credit card balances and certain costly loans can grow quickly. The interest you pay may exceed what you could reasonably expect to earn from investments.
For instance, imagine that an investment might earn a positive return, but your outstanding debt carries a much higher interest rate. Paying down that debt could improve your financial position more reliably than taking additional investment risk.
This does not mean every loan must be repaid before you invest. Some debts have relatively low interest rates, and individual situations differ. Instead, compare borrowing costs, emergency needs, and investment risks before deciding how to use your money.
The practical lesson is straightforward: prepare for financial emergencies first, understand your debt, and invest money that fits your broader financial plan.
Tip 3: Start Small and Invest Regularly
You do not need a large amount of money to begin learning about investing. The amount required depends on the investment product, account rules, fees, and minimum contribution requirements. Some options allow relatively small contributions.
Starting small gives you time to learn how investments work without committing money you need for daily life. It also helps you build a habit that may become easier to maintain as your income grows.
Choose an Affordable Monthly Amount
Look at your income and essential expenses. After allowing for bills, debt payments, emergency savings, and other responsibilities, decide whether any money is available for investing.
Suppose someone can comfortably set aside 50 units of currency each month. They might begin with that amount, provided their chosen investment permits it and the fees are reasonable. If their income increases later, they could consider increasing the contribution.
The example is only illustrative. The right amount for you may be lower, higher, or zero until your financial situation improves.
Understand the Benefit of Regular Investing
Regular contributions can make investing more manageable because you do not have to decide what to do with a large amount all at once. Investing a fixed amount at regular intervals is often called periodic investing.
When prices are lower, a fixed contribution can buy more units of an investment. When prices are higher, the same contribution buys fewer units. However, this method does not guarantee profits or prevent losses, and it does not guarantee better results than investing a lump sum.
The key benefit for beginners is the routine. A realistic plan can help you avoid waiting endlessly for the perfect moment to invest.
You should also review transaction charges, fund expenses, and other costs. If your contribution is very small, fees may take a meaningful share of it. Choose an approach that makes sense after costs.
Tip 4: Learn About Investment Options Before Choosing One
Another essential part of investing money for beginners is understanding what you are buying. An investment should never be selected only because a friend recommended it or an online personality claimed it would rise in value.
Different investments have different risks, costs, time requirements, and possible returns. Learning the basic differences can help you avoid unsuitable choices.
Stocks
A stock represents ownership in a company. When you buy a share, you own a small part of that business. You may benefit if the company grows and its share price increases. Some companies also pay dividends.
However, a stock’s price can fall because of business problems, economic conditions, changing customer demand, or other factors. Individual company shares can be especially risky if most of your money depends on one business.
Before buying a stock, learn how the company earns money, understand its financial position, and consider whether its price makes sense. Never assume that a popular company is automatically a good investment at every price.
Bonds
A bond is generally a loan made to a government, company, or another issuer. In return, the issuer usually agrees to make interest payments and repay the principal according to the bond’s terms.
Bonds have their own risks. An issuer might fail to make payments, market interest rates can affect bond prices, and inflation may reduce the purchasing power of future payments. Different bonds can have very different levels of risk.
Therefore, do not assume that every bond is safe simply because it is not a stock.
Mutual Funds and Exchange-Traded Funds
Mutual funds and exchange-traded funds, commonly called ETFs, collect money from investors and use it to hold a group of investments. Depending on the fund, those investments may include stocks, bonds, or other assets.
Some funds follow a market index. Others use an active management strategy or focus on a particular industry. A broadly diversified fund can provide exposure to many investments through a single product, but not every fund is well diversified.
Before investing, examine the fund’s holdings, fees, investment objective, and risks. Two funds with similar names may follow very different strategies.
Other Investment Choices
Some people also consider property, deposits, government securities, or commodities. Each option has different features and may be suitable for different goals.
For example, property can involve maintenance costs and may take time to sell. Deposits may offer more predictable terms, but inflation can reduce the real value of their returns. Commodities can experience large price movements and may not generate regular income.
The best choice is not necessarily the investment with the highest advertised return. It is the option you understand, can afford, and can hold in line with your financial goals.
For further learning, read Investor.gov’s guide to investment products.
Tip 5: Understand Risk and Diversify Your Investments
Every investment involves some form of risk. Prices can change, businesses can struggle, interest rates can move, and economic conditions can affect returns. Even a carefully prepared investment plan cannot remove all uncertainty.
Understanding risk does not mean avoiding every investment that can lose money. Instead, it means choosing a level of risk that fits your financial goals, time horizon, and ability to handle losses.
Do Not Put All Your Money in One Investment
Diversification means spreading your money across different investments rather than depending entirely on one asset or company. If one investment performs poorly, other holdings may help reduce the effect on your overall portfolio.
Imagine a person who invests all their money in a single company’s shares. If that company experiences serious financial trouble, the person’s entire investment could be affected.
Now imagine another person who holds a suitable mix of investments across different companies and asset types. A problem affecting one holding may have a smaller effect on the overall portfolio, although losses can still occur across many investments at once.
Diversification is not a promise of profit. It is a way to manage some investment risks.
Match Risk to Your Time Horizon
Your time horizon is the period during which you expect to keep money invested before using it. Someone investing for a goal many years away may be able to tolerate more short-term market movement than someone who needs the money soon.
However, a long time horizon does not make every risky investment appropriate. Your income stability, financial responsibilities, and comfort with possible losses also matter.
Consider how you would react if your investment value fell substantially. If a decline would force you to sell or prevent you from meeting essential expenses, you may need a more cautious plan.
Review the Whole Portfolio
Do not judge your investment plan by looking at one holding in isolation. Consider how all your investments work together.
For example, owning several funds does not necessarily mean you are diversified. If those funds hold many of the same companies, your portfolio may still depend heavily on a small group of businesses.
Read more about asset allocation and diversification to understand how investment choices can work together.
A Simple Example: Turning a Plan Into a Habit
Imagine two fictional beginners, Alex and Sam. Both want to build wealth over the long term, but they approach investing differently.
Alex follows investment trends on social media and frequently changes investments after seeing other people discuss quick profits. Alex does little research and has not kept enough emergency savings.
Sam begins by reviewing monthly expenses, building emergency savings, and learning about different investment options. Sam chooses an affordable contribution and researches the risks and fees before investing. Sam then reviews the plan periodically instead of reacting to every market movement.
Neither approach guarantees a particular result. Markets can rise or fall regardless of how carefully someone plans. However, Sam’s process is designed to reduce avoidable mistakes and keep financial goals at the centre of investment decisions.
This example highlights an important lesson: successful investing is not only about selecting assets. It is also about building habits, managing risk, and making decisions you can maintain.
Tip 6: Learn the Power of Compound Growth
One of the most useful ideas in investing money for beginners is compound growth. It means earning returns on your original investment and, when those returns remain invested, potentially earning returns on them as well. Over time, this process can help an investment grow, although actual results depend on market performance, fees, taxes, and other factors.
You do not need to be a financial expert to understand this idea. Imagine planting a small tree. At first, the tree grows slowly. As time passes, it may become larger and produce more branches. Compound growth works in a similar way: growth can build on earlier growth when returns are reinvested.
However, investments do not grow at a fixed rate every year. Some years may bring gains, while others may bring losses. Compounding describes how reinvested returns can accumulate; it does not guarantee that your investment will increase.
How Compound Growth Works
Suppose you invest 1,000 units of currency and earn a hypothetical annual return of 5%. If the return is earned and reinvested, your investment would grow to 1,050 after one year. In the second year, a 5% return on that new amount would bring it to 1,102.50.
The difference may look small at first. Over a longer period, however, returns on previous returns can make a noticeable difference.
Consider this simplified example:
| Year | Hypothetical investment value |
|---|---|
| Starting amount | 1,000 |
| After 1 year | 1,050 |
| After 5 years | 1,276 |
| After 10 years | 1,629 |
| After 20 years | 2,653 |
These figures assume a steady 5% annual return, with no additional contributions, fees, or taxes. They are illustrations, not predictions of actual investment performance.
Why Starting Early Can Help
Time gives compounding more opportunity to work. Someone who starts investing earlier may have more years for returns to accumulate than someone who starts later, assuming comparable contributions and returns.
For example, a person who begins putting money aside in their twenties has a longer potential investment period than someone who begins in their forties. That does not mean everyone must start immediately regardless of their circumstances. Paying essential bills, managing expensive debt, and preparing for emergencies remain important.
The practical lesson is to start when your financial situation allows you to invest responsibly. Even small contributions can help you build a consistent habit. Increase them when your income permits, and avoid taking excessive risks simply because you want faster growth.
You can explore the mathematics of compound interest with the Investor.gov compound interest calculator.
Tip 7: Keep Learning and Avoid Emotional Investing
The final tip is to keep learning while controlling your emotions. Markets can rise sharply, fall unexpectedly, and move sideways for long periods. Beginners sometimes feel excited when prices increase and frightened when prices decline. These feelings can lead to rushed decisions.
Investing money for beginners becomes easier to manage when you create a process before making investment decisions. Instead of reacting to every headline, decide what information matters, how often you will review your investments, and what circumstances would justify a change in your plan.
Do Not Follow Every Online Recommendation
Social media can introduce you to useful financial concepts, but it can also spread misleading claims. Someone may promote an investment because they own it, receive payment for promoting it, or want others to buy after they have already purchased it.
Before acting on a recommendation, ask yourself a few questions. Do I understand the investment? What could cause its value to fall? What fees apply? Is the person providing balanced information about possible losses? Can I verify the claims using reliable sources?
Be especially careful when someone promises guaranteed high returns, pressures you to act immediately, or asks you to send money through an unfamiliar channel. High returns with no risk are not a realistic expectation for ordinary market investments.
Create a Simple Investment Review Routine
You do not need to check investment prices every hour. For many long-term investors, frequent checking creates unnecessary stress and encourages impulsive decisions.
Instead, choose a regular review schedule that suits your investments and financial goals. During a review, consider whether your goals have changed, whether your contributions remain affordable, whether your investment mix is still suitable, and whether fees or other conditions have changed.
A review does not automatically mean you should buy or sell something. Sometimes the most sensible decision is to continue following your existing plan.
Learn From Mistakes Without Chasing Losses
Every investor can make mistakes. You might buy something you do not fully understand, pay more in fees than expected, or discover that an investment is riskier than you thought.
The important thing is to learn from the experience. Identify what went wrong, check the facts, and decide whether your process needs to change. Avoid trying to recover a loss quickly by taking even greater risks.
Investing is a long-term learning process. Good habits, careful research, and patience can help you make better decisions, even though they cannot eliminate investment risk.
Common Investing Mistakes Beginners Should Avoid
Learning what to do is important, but knowing what to avoid can be just as valuable. Many beginners lose money not because investing is impossible to understand, but because they make decisions without a clear plan. The following mistakes can affect your financial progress, so it is worth learning about them before you invest.
Investing Money You Cannot Afford to Lose
One of the biggest mistakes is investing money needed for rent, food, bills, education, or other essential expenses. Investments can lose value, and you may have to sell at a loss if you need cash unexpectedly.
Before investing, make sure your everyday needs are covered and that you have a suitable emergency reserve. Do not borrow money simply to invest in a risky asset unless you fully understand the consequences and can afford the potential losses.
Expecting Quick Profits
Investing is not a reliable way to become wealthy in a few days or weeks. Some investments experience rapid price increases, but they can also fall just as quickly.
If your plan depends on making a quick profit, you may feel pressured to take risks you would otherwise avoid. Focus instead on your financial goals, your investment time frame, and the level of risk you can reasonably handle.
Ignoring Fees and Taxes
Investment costs can reduce your final returns. These costs may include transaction charges, account fees, fund management expenses, and taxes on applicable income or gains.
For example, imagine two similar investments that earn the same gross return. If one has higher ongoing costs, you may keep less of the return from that investment.
Before investing, read the product’s fee information and understand the tax rules that apply to you. Tax treatment varies between countries and may also depend on how long you hold an investment.
Putting Too Much Money Into One Trend
A popular company, industry, cryptocurrency, or other asset may attract attention because its price has recently increased. However, recent performance does not guarantee future gains.
Putting too much money into a single investment can expose you to significant losses if the asset performs poorly. Consider diversification and make sure you understand the risks before committing your money.
Making Decisions Out of Fear
When markets fall, beginners may panic and sell without reviewing their original reasons for investing. When markets rise, they may buy at high prices because they fear missing out.
Neither reaction is a reliable investment strategy. Before making a change, consider your goals, the information available, your financial needs, and whether anything important has changed about the investment itself.
The aim is not to ignore every market movement. It is to make decisions based on evidence and your financial plan rather than fear or excitement.
How to Start Investing: A Simple Step-by-Step Plan
Now that you understand the seven smart tips, you can turn them into a practical process. You do not have to complete everything in one day. Work through each step at a pace that suits your financial situation.
Step 1: Review Your Financial Situation
Start by writing down your monthly income, essential expenses, debts, savings, and existing investments. This will help you understand how much money you can reasonably allocate toward your goals.
Be honest about your expenses. If you regularly spend more than you earn, work on improving that situation before increasing your investment contributions.
Step 2: Choose One Clear Goal
Select a goal that matters to you. It might be building long-term wealth, preparing for retirement, or saving for a future purchase.
Write down your target amount and expected time frame. A clear goal makes it easier to choose an appropriate investment strategy and measure progress.
Step 3: Build Financial Protection
Set aside money for emergencies and develop a plan for expensive debt. The size of your emergency reserve should reflect your essential expenses, income stability, and responsibilities.
This step matters because an investment plan is harder to maintain if an unexpected expense forces you to sell assets at the wrong time.
Step 4: Learn About Suitable Investment Products
Research the investments available to you. Compare their risks, potential returns, fees, liquidity, and minimum investment requirements.
Use official regulator websites, product documents, and reliable educational resources. If you do not understand how an investment works, take more time to learn before committing money.
Step 5: Select an Affordable Contribution
Decide how much you can invest regularly without affecting essential expenses or emergency savings.
You may begin with a modest amount. The goal is to develop a sustainable habit rather than impress other people with the size of your investment.
Step 6: Write Down Your Investment Rules
Create a short plan explaining why you are investing, what types of investments you intend to hold, how much risk you can accept, and when you will review your progress.
Include conditions that would justify changing the plan. For example, a major change in your financial circumstances may require a different approach.
Having written rules can help you avoid making decisions based on every new market prediction.
Step 7: Review and Improve
Check your progress periodically. Compare your current situation with your original goals and consider whether your contribution amount remains suitable.
Learn from reliable sources and update your knowledge as financial products and rules change. Avoid making unnecessary changes merely because another investment has recently performed better.
This process is a starting framework, not a guarantee of success. Your actual investment choices should reflect your circumstances, local regulations, and financial needs.
How Much Money Should a Beginner Invest?
There is no single amount that every beginner should invest. Your income, essential expenses, existing debt, savings, financial responsibilities, and investment options all affect the answer.
Someone with a stable income and adequate emergency savings may be ready to invest a regular amount. Someone who is struggling to cover essential bills may benefit more from building financial stability first.
A useful starting point is to calculate the money left after essential expenses, debt payments, and planned savings. Then decide whether a portion can be invested without creating financial pressure.
For example, imagine that you have 200 units of currency left after meeting your monthly needs and setting aside money for emergencies. You might choose to invest part of that amount and retain the rest for other goals. The exact split depends on your situation, and there is no universal percentage that suits everyone.
Also consider investment minimums and fees. An investment that looks affordable at first may become less attractive if transaction costs consume a large share of each contribution.
The most important principle is affordability. Do not measure your progress against someone else’s portfolio. Focus on building a plan you can maintain through different stages of life.
How to Measure Your Investing Progress
Investment progress is not only about whether your portfolio is showing a profit today. It also includes the habits and financial improvements that support your long-term goals.
Track Your Contributions
Record how much money you add to your investments over time. This helps you distinguish between the money you contributed and any gains or losses resulting from investment performance.
If you increase your contributions when your income grows, you may improve your ability to work toward your goals without depending entirely on market returns.
Review Returns After Costs
When evaluating performance, consider fees, taxes, and inflation where relevant. An investment may increase in nominal value while its purchasing power grows more slowly.
Compare investments fairly. For example, comparing a high-risk stock fund with a cash savings account without considering risk and time horizon can lead to misleading conclusions.
Check Whether Your Portfolio Still Fits Your Goals
Your circumstances can change. You may start a family, change jobs, move to a different country, or approach a major financial goal.
As these changes occur, review your investment choices. A portfolio that once suited your needs may no longer be appropriate.
Avoid Measuring Success Every Day
Daily price changes can make a long-term investment plan feel more stressful than necessary. Unless your strategy requires closer monitoring, use a regular review schedule rather than reacting to every movement.
Progress should be measured against your financial plan, not against the latest online investment trend.
Frequently Asked Questions About Invest Money For Beginners
1. What Is the Best Way to Invest Money for Beginners?
The best starting point is to set clear goals, build emergency savings, understand your debts, and learn about suitable investment options. Choose investments based on your time horizon, risk tolerance, and financial circumstances. Diversified funds may be worth researching, but they are not automatically suitable for everyone and can lose value.
2. Can I Start Investing With a Small Amount of Money?
Yes, some investment products allow relatively small contributions. However, minimum investment requirements and fees vary. Start with an amount you can afford after covering essential expenses and financial priorities. A small, consistent contribution can help you build an investing habit, but it does not guarantee a particular result.
3. Is Investing Riskier Than Saving Money?
Investing generally involves the risk of losing money because the value of assets can rise or fall. Savings accounts may provide more predictable balances, subject to their terms and applicable protections. However, savings can lose purchasing power when inflation exceeds the interest earned. The appropriate balance between saving and investing depends on when you need the money and how much risk you can accept.
4. How Long Should I Keep My Money Invested?
The right time frame depends on your financial goal and the investment you choose. Long-term goals may allow you to tolerate more short-term market fluctuations, while money needed soon generally calls for greater attention to stability and accessibility. There is no single holding period that guarantees a profit. Review your plan as your needs change.
5. What Is Compound Growth in Investing?
Compound growth occurs when returns remain invested and future returns can build on the earlier growth. For example, if an investment earns a return and that return is reinvested, the next period’s return may apply to a larger balance. Actual investment returns fluctuate, and fees, taxes, losses, and withdrawals can affect the result.
6. Should Beginners Invest in Individual Stocks or Funds?
Individual stocks give you exposure to specific companies, while many funds hold multiple investments. A suitably diversified fund may reduce the risk associated with depending on a single company, although it cannot eliminate market risk. Your choice should depend on your knowledge, goals, costs, and ability to handle losses.
7. Can I Lose All My Invested Money?
Yes, depending on the investment. Some assets can lose most or all of their value, and certain products may involve additional risks. Diversification can help reduce dependence on one investment, but it cannot guarantee that you will avoid losses. Understand the product and its risks before investing.
Final Thoughts: Build Your Financial Future One Step at a Time
Invest Money For Beginners is a topic that becomes easier when you approach it with patience and a clear plan. You do not need to predict every market movement or find an investment that promises extraordinary returns. You need to understand your goals, protect your financial stability, and make decisions based on reliable information.
Start by reviewing your income and expenses. Build an emergency fund, manage expensive debt, and learn how different investment products work. Then choose a suitable amount to invest, understand the costs, and consider diversification. As your knowledge and financial circumstances change, review your strategy.
Remember that investing involves risk. Past performance does not guarantee future returns, and even a well-designed plan can experience losses. Avoid pressure from people promising quick profits, and never invest in something you cannot explain or do not understand.
Your first step does not need to be large. It needs to be thoughtful. Set one clear financial goal today, identify what you need to do before investing, and create a realistic plan you can follow.
Over time, consistent contributions, informed decisions, and careful risk management can help you work toward greater financial security. Start with what you know, keep learning, and allow your plan to develop as your circumstances change.
REFRANCE-Invest Money For Beginners 7 Smart Tips Invest Money For Beginners 7 Smart Tips Invest Money For Beginners 7 Smart Tips Invest Money For Beginners 7 Smart Tips Invest Money For Beginners 7 Smart Tips Invest Money For Beginners 7 Smart Tips Invest Money For Beginners 7 Smart Tips Invest Money For Beginners 7 Smart Tips Invest Money For Beginners 7 Smart Tips Invest Money For Beginners 7 Smart Tips Invest Money For Beginners 7 Smart Tips Invest Money For Beginners
7 Smart Tips Invest Money For Beginners 7 Smart Tips Invest Money For Beginners 7 Smart Tips Invest Money For Beginners 7 Smart Tips Invest Money For Beginners 7 Smart Tips Invest Money For Beginners 7 Smart Tips Invest Money For Beginners 7 Smart Tips Invest Money For Beginners 7 Smart Tips Invest Money For Beginners 7 Smart Tips Invest Money For Beginners 7 Smart Tips Invest Money For Beginners 7 Smart Tips Invest Money For Beginners 7 Smart Tips Invest Money For Beginners 7 Smart Tips Invest Money For Beginners
7 Smart Tips Invest Money For Beginners 7 Smart Tips Invest Money For Beginners 7 Smart Tips Invest Money For Beginners 7 Smart Tips Invest Money For Beginners 7 Smart Tips Invest Money For Beginners 7 Smart Tips Invest Money For Beginners 7 Smart Tips Invest Money For Beginners 7 Smart Tips Invest Money For Beginners
7 Smart Tips Invest Money For Beginners 7 Smart Tips Invest Money For Beginners 7 Smart Tips Invest Money For Beginners 7 Smart Tips Invest Money For Beginners 7 Smart Tips Invest Money For Beginners 7 Smart Tips Invest Money For Beginners 7 Smart Tips Invest Money For Beginners 7 Smart Tips Invest Money For Beginners 7 Smart Tips Invest Money For Beginners 7 Smart Tips Invest Money For Beginners 7 Smart Tips Invest Money For Beginners 7 Smart Tips Invest Money For Beginners 7 Smart Tips Invest Money For Beginners 7 Smart Tips Invest Money For Beginners 7 Smart Tips Invest Money For Beginners 7 Smart Tips Invest Money For Beginners
7 Smart Tips Invest Money For Beginners 7 Smart Tips Invest Money For Beginners 7 Smart Tips Invest Money For Beginners 7 Smart Tips Invest Money For Beginners 7 Smart Tips Invest Money For Beginners 7 Smart Tips Invest Money For Beginners 7 Smart Tips Invest Money For Beginners 7 Smart Tips Invest Money For Beginners 7 Smart Tips Invest Money For Beginners 7 Smart Tips Invest Money For Beginners
7 Smart Tips Invest Money For Beginners 7 Smart Tips Invest Money For Beginners 7 Smart Tips Invest Money For Beginners 7 Smart Tips Invest Money For Beginners 7 Smart Tips Invest Money For Beginners 7 Smart Tips Invest Money For Beginners 7 Smart Tips Invest Money For Beginners 7 Smart Tips Invest Money For Beginners 7 Smart Tips Invest Money For Beginners
2 thoughts on “Invest Money For Beginners 7 Smart Tips”